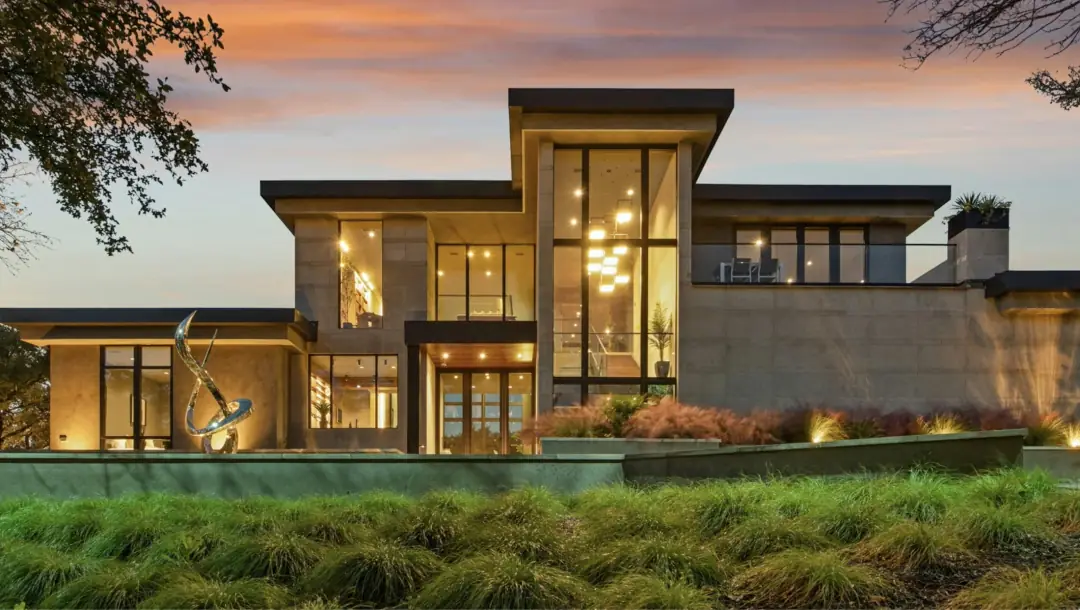
A primary residence
IllustrationHow a surgeon and an architect planned the second half of their mortgage
They could afford the payment. What they did not want was a payment that still depended on his operating schedule at sixty-two.
- Committed at purchase
- $2,000,000against $800,000 traditionally
- Payment, years 1–15
- $16,266.67a month, interest only
- From year 16
- $0 projectedthe policy is projected to fund $27,176.61 a month
The situation
A thirty-year mortgage taken at 47 runs until 77. He expects to scale back at around 60 and stop operating a few years after that. On a traditional loan the payment would be $19,391.83 a month for all thirty years, the last fifteen of them paid from savings or from her practice.
Their question was not whether they could afford the house. It was what the second half of the mortgage would be paid with.
The structure
They put $800,000 down and took a $3,200,000 mortgage that is interest only for fifteen years. Alongside it they contributed $1,200,000 to an indexed universal life policy on her life, with a bank financing further premiums. In total they committed $2,000,000 at closing, half the price of the home.
For the first fifteen years they pay $16,266.67 a month. In year sixteen, when he is 62, the bank that financed the premiums has been repaid and the policy is projected to provide $370,000 a year. The mortgage payment at that point is $27,176.61 a month, or $326,119 a year.
What it gave them
A payment of $16,266.67 a month for fifteen years, against $19,391.83 on a traditional loan. From year sixteen the scheduled payment is designed to be met by the policy, not by his operating schedule.
When the mortgage is repaid in year thirty, projected policy cash of $370,000 a year continues to them. Over the life of the loan they put in $4,928,000 of their own money, against $7,781,060 traditionally.
How it was underwritten
As one transaction: their finances, her health, the lender’s terms and the bank’s, together. The plan was modeled on a conservative profile before it was proposed, and it is built with margin. Projected policy cash of $370,000 a year stands against $326,119 of mortgage payments.
After closing, the policy, the bank loan and the collateral are reviewed against the plan every year.
Why it suited them
They had the capital, a long horizon, and a specific aim the structure addresses: a large fixed payment that should not depend on a physically demanding career. They reviewed the proposal and the carrier illustration with their CPA before signing.
The numbers
Line by line
At purchase
Years 1 to 15
Years 16 to 30
Year 31 onward
The whole picture, through year 62
Illustration. Both cases assume a 6.1% mortgage note rate, a 20% down payment, and no investment of money kept or saved. The program’s projected policy cash is a quoted figure scaled to the policy contribution; it is not derived by this model and is not guaranteed. The base case assumes no further personal premiums, financing interest or bank-exit payments. Property taxes, home insurance, maintenance, closing and advisory costs and tax effects are excluded.
How each line is calculated
- Traditional payment. Principal × r ÷ (1 − (1 + r)−360), where r is the annual rate divided by 12.
- Program, years 1 to 15. Principal × r. Interest only; the balance stays at $3,200,000.
- Program, years 16 to 30. The full $3,200,000 amortized over the remaining 180 months, which is why the payment is 67% higher than in the first fifteen years.
- Projected policy cash. $370,000 a year on a $1,200,000 contribution in the reference case, scaled in proportion. It covers 113% of the later mortgage payment as illustrated.
- Total you put in. Initial capital plus every mortgage payment not funded by projected policy cash.
Their cash position, year by year
Everything paid in, less projected policy cash received.
By qualification
Find out if it is open to you.
Three ranges tell you where you stand against the published criteria. If you meet them, Kent Chesley will speak with you personally.
Prefer to talk? Call him directly at 949-293-8686.