Skip to content
Family Office Mortgage

The mortgage designed for people with high net worth

A mortgage designed to pay itself. Then pay you.

Pay interest for fifteen years. Then a structured financial product you fund at closing is designed to make the payments, and to keep paying you after the loan is gone.

On a $4,000,000 home

Years 1–15
$17,333a month, from you
Years 16–30
$0from you, projected
Year 31 on
$340,000a year to you, tax-advantaged, for life

Offered by qualification, to households with $5M or more. About half the home’s price is committed at closing. Later figures are projected.

A jumbo mortgage paired with a structured financial product, for households with $5M or more.

Make it yours

Illustration

For a $4,000,000 home

Enter your price. Every figure on this page is recalculated for your home.

Committed at purchase
$2,000,000$800,000 down payment and $1,200,000 into the financial instrument. A traditional purchase commits $800,000.
Your payment, years 1–15
$17,333a monthInterest only, 14.3% below the traditional $20,226.
Your payment, years 16–30
$0a month, projectedA projected payout of $340,000 a year is designed to make the $334,505 a year of mortgage payments.
Year 31 on
$340,000a year to you, tax-advantaged, for lifeThe mortgage is repaid. The projected payout, the full amount of the payoff payments, now comes to you.
How these figures are calculated

The mortgage figures are arithmetic: 20% down, an 80% mortgage at an assumed 6.5% note rate in both cases, a 30-year amortizing loan against a loan that is interest only for 15 years and then amortizes over the next 15.

Projected payout is not calculated by this site. It scales a quoted illustration of $340,000 a year on a $1,200,000 contribution in proportion to the contribution for your home. It is not guaranteed, and an actual proposal uses the issuer’s illustration for a specific person. Property taxes, home insurance, maintenance, closing and advisory costs and tax effects are not included.

The full comparison

The advantage of capital

You do not buy like everyone else. Why borrow like them?

The thirty-year mortgage was designed for buyers who must borrow as much as they can and repay it from a salary. You have something they do not: capital. The Family Office Mortgage is built to use it.

Commit more on the first day, and a funded financial instrument — a premium-financed indexed universal life insurance policy — is designed to take over the payments halfway through, then keep paying you. It is the structure a family office puts around a significant purchase, built from three regulated parts: a home mortgage, that policy from a major issuer, and a bank loan that finances part of its funding.

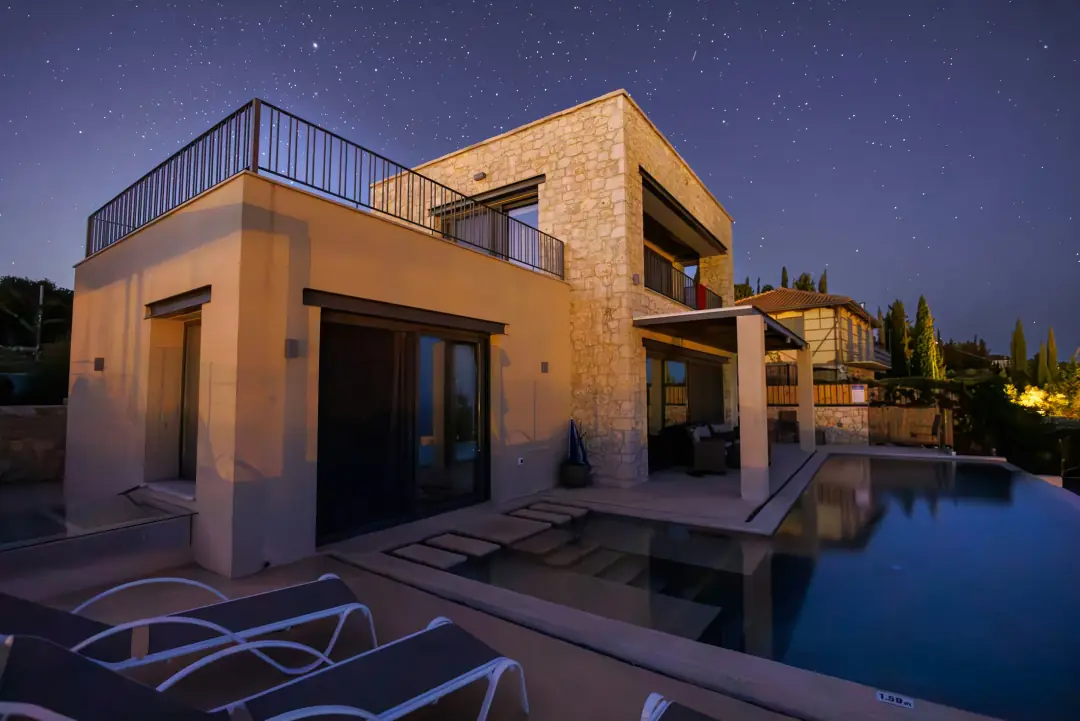
A white modern residence, lit from within at dusk
  1. I

    A mortgage

    From your lender or one we introduce. Interest only for fifteen years, then repaid over the fifteen that follow.

  2. II

    A financial instrument

    A premium-financed indexed universal life insurance policy, funded with about 30% of the home’s price from you, with a bank financing the rest of its funding.

  3. III

    A plan

    The instrument has fifteen years to build. From year sixteen it is designed to fund the mortgage, and then to keep paying you.

01The timeline

Who pays, year by year.

Illustration

$2M

committed at purchase

Who makes the mortgage payment in each yearYears 1 to 15: the household pays $208,000 a year in interest. Years 16 to 30: the projected payout of $340,000 a year funds the $334,505 mortgage payment. Years 31 to 62: the projected payout goes to the household. A traditional mortgage would cost $242,714 a year for 30 years.
You pay The instrument pays Cash to youAll payout figures projected

01At purchase

You commit half the price.

$800,000 goes to the home as a down payment. $1,200,000 goes into a structured financial product, and a bank finances its further funding. A lender provides a $3,200,000 mortgage.

About half the price, committed on the first day.

02Years 1 to 15

You pay interest only on the home mortgage.

$17,333 a month, against $20,226 for a traditional loan. Meanwhile the financial instrument has fifteen years to build value.

That is $2,893 a month less than a traditional payment, for fifteen years.

03Year 16

The instrument is designed to take over.

The bank has been repaid, and the instrument is projected to provide $340,000 a year. The mortgage now costs $334,505 a year. The projected source of that payment is the instrument, not your income.

The instrument we use is a premium financed indexed universal life policy issued by a major insurance company. Like all products it has both benefits and risks — please review the Disclosures page. The cases illustrated on this website are examples of what we structure for family offices and individuals; only a full proposal made to you with a fully compliant carrier illustration and disclaimers may be taken as a formal proposal.

The payout is designed to the payment: $340,000 projected against $334,505 due.

04Year 30

The mortgage is repaid.

Across thirty years you will have paid $5,120,000 yourself, against $8,081,424 with a traditional mortgage. Either way, you own the home outright.

That is $2,961,424 less from your own pocket.

05Years 31 to 62

The cash continues.

With no mortgage left to pay, the projected payout of $340,000 a year is yours: the full amount of the payments it was making, to you — taken as policy loans, which are generally not taxed as income while the policy stays in force.

The illustrated period. The instrument is reviewed against its plan every year.

By qualification

Is it open to you?

The program is offered to households that meet its published criteria. Three ranges tell you where you stand, before you give a name.

Three ranges. Your answer appears here, before you give a name.

02What it changes

What your capital does

  1. 01

    A lower payment from the first month.

    Interest only for fifteen years. In the reference case, $17,333 a month instead of $20,226.

  2. 02

    A mortgage designed to pay itself.

    From year sixteen, the projected payout is designed to make the payments. Your income stops being the plan.

  3. 03

    More back than you put in.

    After the loan is repaid, the projected payout continues: $340,000 a year through year 62. In the reference case you put in $5,120,000 and the instrument is projected to pay you $10,962,422.

  4. 04

    Something left for the family.

    A benefit is designed to pass to your family, alongside a home that is paid for.

  5. 05

    Half your capital stays yours.

    If you would otherwise pay cash, half the purchase price never leaves your accounts.

03Beside a traditional mortgage

The comparison

Illustration

Reference case: a $4,000,000 purchase.

The bottom line, projected through year 62

You put in $5,120,000. The financial instrument is projected to pay $5,017,578 of your mortgage, then pay you $10,962,422. Everything you put in comes back, and $5,842,422 more.

A traditional mortgage on the same home takes $8,081,424 from you over 30 years.

Traditional mortgageFamily Office Mortgage

At purchase

Down payment$800,000$800,000
Into the financial instrument—$1,200,000
Total committed$800,000$2,000,000

Years 1 to 15

Monthly mortgage paymentProgram: interest only$20,226.18$17,333.33
Mortgage balance at year 15$2,321,893$3,200,000

Years 16 to 30

Monthly mortgage paymentProgram: principal and interest over 15 years$20,226.18$27,875.44
Projected payout, per year—$340,000
What you pay, per month$20,226.18$0 projected
Projected cash left over, per year—$5,495

Year 31 onward

Mortgage paymentsNoneNone
Projected payout, per year, through year 62—$340,000

The whole picture, through year 62

Total you put in$8,081,424$5,120,000
Mortgage payments made by the instrument, projected—$5,017,578
Projected payout paid to you, years 16 to 62—$10,962,422
Cash received, less cash put in−$8,081,424+$5,842,422 projected

Illustration. Both cases assume a 6.5% mortgage note rate, a 20% down payment, and no investment of money kept or saved. The program’s projected payout is a quoted figure scaled to the contribution to the instrument; it is not derived by this model and is not guaranteed. The base case assumes no further personal funding of the instrument, financing interest or bank-exit payments. Property taxes, home insurance, maintenance, closing and advisory costs and tax effects are excluded.

How each line is calculated
  • Traditional payment. Principal × r ÷ (1 − (1 + r)−360), where r is the annual rate divided by 12.
  • Program, years 1 to 15. Principal × r. Interest only; the balance stays at $3,200,000.
  • Program, years 16 to 30. The full $3,200,000 amortized over the remaining 180 months, which is why the payment is 60.8% higher than in the first fifteen years.
  • Projected payout. $340,000 a year on a $1,200,000 contribution in the reference case, scaled in proportion. It covers 101.6% of the later mortgage payment as illustrated.
  • Total you put in. Initial capital plus every mortgage payment not funded by projected payout.

04How you are protected

We know the risks. Managing them is the work.

A mortgage paired with a bank-financed instrument has moving parts. Our team has structured hundreds of transactions, and each one is underwritten and managed so that you are protected.

  • Underwritten before it is offered

    We underwrite each transaction as a whole (the purchase, the instrument’s design and the financing) before anything is proposed to you.

  • Modeled conservatively

    Designs are tested with no growth credited in their first two years, the worst timing there is, and run across many market paths.

  • Sized to the payment

    In the reference case, a projected payout of $340,000 a year is designed against $334,505 of mortgage payments.

  • Reviewed every year

    The instrument’s values, the bank loan and the collateral are checked against the plan each year, so adjustments are made early.

  • Open to your advisors

    Before you sign anything, your CPA and your attorney receive the issuer’s full proposal, a year-by-year spreadsheet that matches it, and a disclosure statement of about seventy pages.

06By qualification

Who qualifies

  1. 01

    A home of $4M or more

    The program is built for purchases of $4M and above. The structure, and the team’s attention to each case, are sized to homes at that level.

  2. 02

    Assets of $5M or more

    Total household assets, not counting the home being purchased. The program commits about half the purchase price up front, which a household of this size does comfortably.

  3. 03

    Household income of $500,000 or more

    You carry the interest-only payment yourself for the first fifteen years. The program is built around income of $500,000 or more a year.

  4. 04

    Capital for about half the purchase price

    Roughly 20% as the down payment and up to 30% as the contribution to the financial instrument. Where the instrument needs less, more goes to the down payment. On a $4M home that is $2M at closing.

07Your CPA and attorney

For your advisors

The people who advise you should see everything we see. We have written a technical brief for them: how the three loans fit together, how each case is underwritten, and the documents they will receive.

08The team

The people behind it.

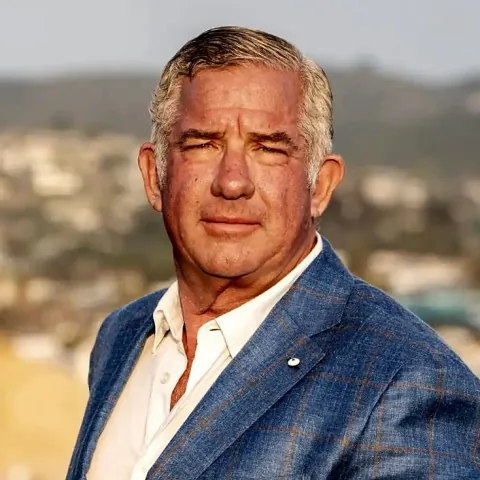
Kent Chesley

Real estate advisory

Kent Chesley

DRE #02283898

Berkshire Hathaway HomeServices California Properties

A Harvard-trained economist who spent decades in institutional finance before returning to the coast he grew up on.

949-293-8686

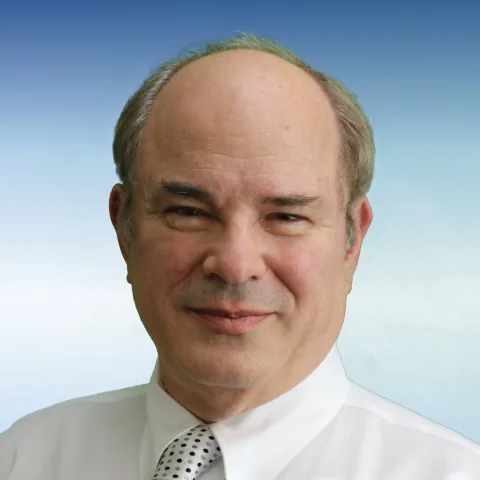
Paul Finestone

President & Founder, Finestone VFO

Paul Finestone

CA Insurance Lic. #0748510 · NPN 1540337

Finestone Virtual Family Office

President and founder of Finestone VFO, a virtual family office with a national network of tax, legal and financial specialists.

747-233-4805

By qualification

Find out if it is open to you.

Three ranges tell you where you stand against the published criteria. If you meet them, Kent Chesley will speak with you personally.

Prefer to talk? Call him directly at 949-293-8686. Kent Chesley, DRE #02283898.

Sell homes at this level? The page for agents.

Rather read first? The Letter — one idea a month.

Three ranges. Your answer appears here, before you give a name.